The Texas real estate market is competitive. Whether you’re exploring new neighborhoods in Frisco, planning to upgrade to a bigger home in Katy, or searching for the perfect Hill Country getaway, your dream home may not become available when your current home sells. This timing gap often leaves homeowners facing difficult decisions.
Another option: With a Texas bridge loan, you can buy your new property before selling your current home, so you can make a more competitive offer with greater confidence.
What Is a Bridge Loan?
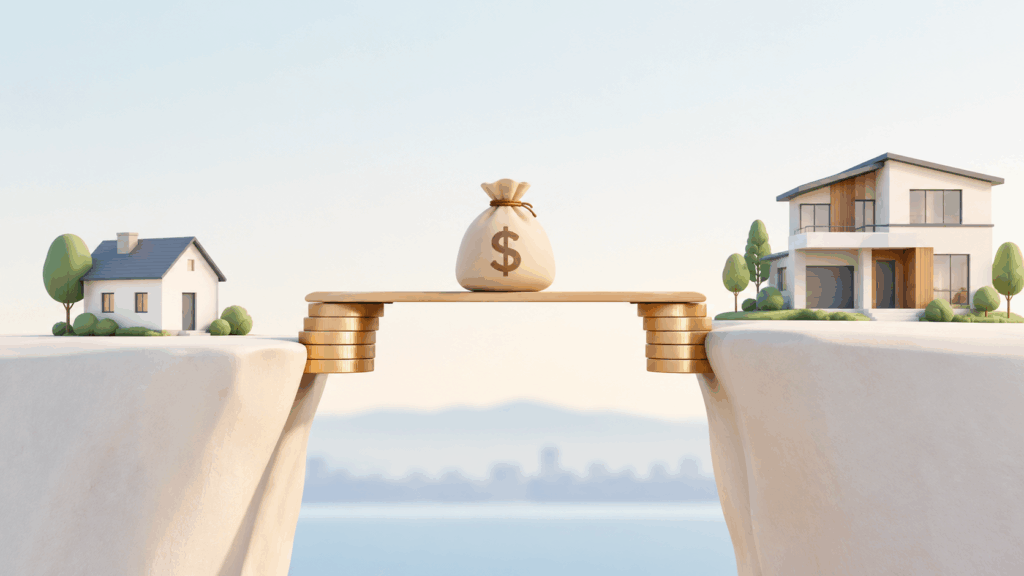
Bridge loan is a type of short-term loan that helps you bridge the gap between buying a new home and selling your current one. Typically lasting 6 to 12 months, a bridge loan allows you to use the equity in your current home to help fund the down payment on your new property. When your current home sells, the proceeds can be used to repay the bridge loan, leaving you with the mortgage on your new home.
Because the loan is temporary, this option is generally best suited for homeowners who plan to sell their existing property. Lenders consider your available home equity, your ability to manage payments while owning both properties, and how easily your current home is likely to sell.
Bridge Loan Trends in Texas
In competitive Texas housing markets, bridge loans can be a valuable option for homebuyers who need to act quickly. When desirable properties become available, buyers may need to move fast to avoid missing out on the opportunity to purchase their next home.
Key demand drivers include:
- Job relocations: Employers relocating to or growing their operations in Texas provide families with limited time to get ready.
- For multiple offers, when they are: Competitive offers: Non-contingent offers are attractive in a multiple-offer situation.
- Equity-rich homeowners: Sellers have a lot of equity they can use to buy their next home.
- Moving families: Upsizing requirements don’t necessarily align with school term or sale dates.
- Move-up buyers: No double move or temporary housing.
With all these market forces in play in Dallas-Fort Worth, Houston, Austin, and San Antonio, bridge financing is the solution for buyers who need certainty, speed, and flexibility.
Why Bridge Loans Make Sense in Texas?
Texas is some of the hottest in the country, so in cities including Austin, Dallas-Fort Worth, Houston, and San Antonio, quality, priced homes go under contract in a matter of days. Sellers in these bustling markets have the luxury of choosing a buyer without strings – you don’t have to sell your house first.
Some things specific to Texas that you should keep in mind:
- High numbers of families and professionals migrating between cities result in potentially relocating right in the middle of your two closings.
- As values increased over the past couple of years, plenty of Texas homeowners have accumulated significant equity, and that equity is the bricks and mortar of a bridge loan.
- No state income tax: Texas does not have a state income tax, so you’ll be able to keep things easier while juggling the two properties.
- More expensive property taxes and insurance: Texas property taxes are some of the highest in the country, and flood, wind, or hail coverage can quickly add up. Save both homes at the same time.
- Title company closings: Since Texas closings are usually completed through a title company, having two closings in a short window of time requires a team that works well together.
- Homestead rules: Texas has extensive homestead protections and certain rules about borrowing against your home, so it’s important to work with a lender who understands the ins and outs of lending in Texas.
How Does a Texas Bridge Loan Work?
The process of arranging a bridge loan can vary slightly by lender, but it typically includes:
- Your lender will review your home’s value and remaining mortgage balance to identify any available equity.
- We will evaluate your credit, income, and debt-to-income ratio, as well as your new home’s financing.
- Tap into your equity. Bridge proceeds provide the funds for the down payment and closing costs on your next property.
- Close and relocate. You buy your new home, settle in comfortably, and ready your old home for sale.
- Sell & payback. When your current home sells, the proceeds will pay off the bridge loan on that property.
Some bridge loans are structured as a second lien on your existing home, while others offer short-term financing with interest-only or deferred payments. Loan terms vary by lender and program, so be sure to review the details carefully.
Main Advantages of Bridge Lending
- Multiple offers: Lose the home sale contingency and get ahead in a multiple-offer situation.
- No double move: Avoid the moving and temporary housing, storage units, and the second move.
- Flexibility: Buy when the right home comes, rather than waiting for your sale date.
- Higher sale price: Get out of the property first, then fix, stage, and sell – on your schedule and without a deadline.
- Less stress: Make the purchase and sale in two easy steps.
Costs and Risks to Consider
Bridge loans are handy, but not cheap. The lender might charge a higher rate for the loan than your normal mortgage loan, as well as origination fees, appraisal and closing costs, and other payments. You might find yourself paying two sets of taxes, utilities, insurance, HOA dues, and other payments.
A slow sale. With property, the longer it takes to sell, the more it costs – especially if you’re not getting the price you want. Protect yourself by listing your house at the right price, using an experienced local agent, building a cash cushion, and creating an exit plan before you borrow.
Who Is a Good Candidate?
If you have substantial equity in your current home, a stable income, excellent credit, and a home that is likely to sell quickly, a bridge loan might be right for you. This type of financing can be particularly useful in competitive Texas housing markets, where buyers may need to act quickly to secure their next home.
Other Options to Explore
Bridge loans aren’t your only option. A home equity line of credit (HELOC), a home equity loan, or a rent-back agreement after selling your home may be another solution, depending on your needs. Because Texas has specific home equity lending restrictions, including limits on combined loan-to-value (CLTV) ratios, an experienced lender can help you understand which option best fits your situation.
Future Growth of Bridge Loans in Texas
These bridge loans in Texas have a promising future. Because Texas continues to grow with new families, new companies, and new investment, more people will require a short-term strategy to purchase first and then sell.
Growth is likely to be shaped by:
- Population and employment growth: Continued migration maintains healthy housing demand.
- Digital lending: Accelerated application and approval processes pave the way for bridge financing.
- Increased home value: Long-term appreciation enhances seller borrowing power.
- Market competition: Buyers will continue to pursue non-contingent offers.
- Product innovation: Lenders might provide flexibility in the terms and structure of the loan.
Timing may be affected by interest rates and market conditions, but the need for flexible financing remains. Reliance Financial is ready to help Texas homeowners navigate this transition by exploring bridge loan options tailored to their needs, with clear guidance on loan terms and costs.
What Reliance Financial Can Do for You?
Buying before selling is a major move, but it doesn’t have to be nerve-wracking when you’re in capable hands. The experts at Reliance Financial will analyze your equity, provide the next steps, and help you develop an action plan that aligns with your needs and your budget. So no matter where you’re headed in DFW, Austin, or Houston, Reliance Financial will give you the confidence to keep moving forward.
Are you ready to get started with a Texas bridge loan? Reach out to Reliance Financial today and discuss your case to get the process started.
Frequently Asked Questions
What is the time period of a bridge loan?
Bridge loan terms are usually six months to a year, but can be shorter or longer with some lenders. Double-check your financing agreement for the expected completion date.
How much equity do I need?
Your current home needs to have a healthy amount of equity, as it helps to secure the loan and determines what the maximum loan amount is.
Can I make an offer without a home sale contingency?
Yes. With bridge financing, you can make a non-contingent offer that appeals to Texas sellers and encourages them to accept your bid today.
What if my home takes longer to sell?
You can extend payments. Talk to your lender about extension options and value your home sensibly from day one.
Are bridge loans more costly than normal mortgages?
Usually, yes. Bridge loans generally involve elevated fees and interest rates compared to standard mortgages, due to their short-term nature and associated risks.
What are the qualifications for a bridge loan?
Qualification is based on credit, income, debt-to-income, and equity. Call Reliance Financial today for a FREE Texas quote.